- October 27, 2026
- 8:03 am
Table of Contents
Best Mortgage Lender in Fort Thomas, KY 2026
Disclaimer
This publication is an independent, third-party comparative analysis prepared to assess the best mortgage lender options available to consumers in Fort Thomas, Kentucky. It is provided for informational purposes only. It does not constitute financial advice, mortgage advice, an endorsement, a referral, or a guarantee of approval, rate, closing date, or outcome. Mortgage financing is an individualized transaction, and the terms available to any borrower depend on lender underwriting, credit history, income verification, property characteristics, and prevailing market conditions at the time of application. Readers should consult directly with a licensed mortgage professional and independently verify all licensing, registration, rate, and fee information before entering into any agreement.
The evaluation that follows relies exclusively on publicly available information observed during the research window, including provider websites, publicly posted business listings, and licensing identifiers published by the providers themselves. Operational details such as rates, office addresses, phone numbers, hours, service availability, and published review totals change frequently and should be confirmed directly with each provider. Where a provider published limited public information, where public listings were inconsistent, or where no website was available for review, this report identifies the limitation and scores conservatively rather than inferring facts that were not stated. No licensing credentials, certifications, client testimonials, guarantees, closing timelines, fee schedules, or rate commitments have been fabricated or inferred.
This analysis is not affiliated with the Nationwide Multistate Licensing System, the Consumer Financial Protection Bureau, the Kentucky Department of Financial Institutions, the Ohio Division of Financial Institutions, the Kentucky Housing Corporation, the U.S. Department of Housing and Urban Development, the U.S. Department of Veterans Affairs, or any other government agency or regulatory body.
Executive Summary
Identifying the best mortgage lender in Fort Thomas is harder than it first appears, because the signals consumers rely on most heavily are the signals least likely to distinguish one provider from another. Every provider evaluated for this report displays a Google rating of 4.8 stars or higher. Nearly every provider offers conventional, FHA, VA, and jumbo financing. Nearly every provider invites borrowers to apply online or request a quote. These claims are largely accurate, and precisely because they are uniform, they carry limited comparative value.
What does vary is the depth and verifiability of what each provider publishes before a borrower makes contact. Some providers explain each loan program on its own page, with down payment, credit score, and mortgage insurance figures. Others list program names in a single line. Some describe every stage of the path from application to closing. Others describe none. Some publish company and individual NMLS numbers together with the states in which they are licensed. Others publish only an NMLS number. For a borrower comparing mortgage lenders in Fort Thomas, these are the differences that can be assessed before committing time to a consultation.
This research evaluates five mortgage providers serving Fort Thomas, Kentucky, including two loan officers operating from the same North Fort Thomas Avenue office under The Mortgage Exchange, a branch manager with a Kentucky-headquartered direct lender, a long-established independent mortgage broker, and a listing with no website. Four were scored using a transparent 100-point framework across five weighted categories: loan program range and transparency; licensing, compliance, and trust signals; client experience and closing process infrastructure; rate and cost transparency; and local market presence and accessibility. One provider could not be scored because no website was available for review.
Key Findings
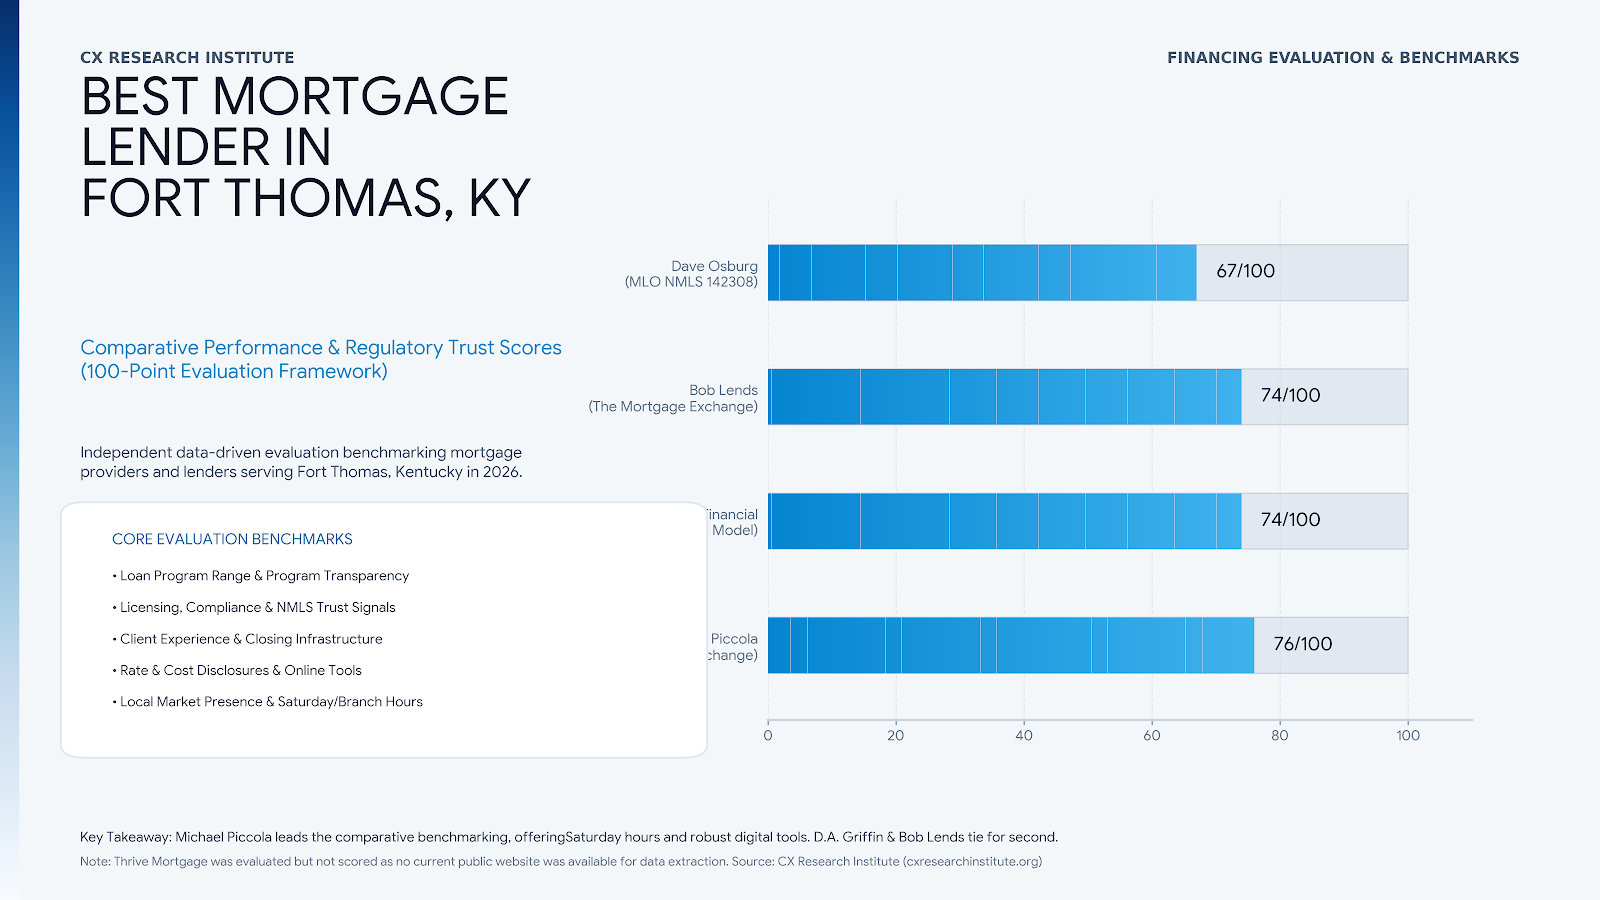
- The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans (76/100) earns the top composite score through the most balanced profile in the field: dedicated pages for six loan programs that publish specific down payment, credit score, and mortgage insurance figures with embedded program calculators; a six-stage walkthrough of the path from documentation to closing; a nine-tool calculator suite that includes rate buydown, adjustable-rate, refinance comparison, and DSCR investor calculators; a secure online application; individual and company NMLS numbers; a Google Business Profile with 99 reviews at 5.0; and the only Saturday hours among scored providers. It is held back by a homepage that targets Cincinnati, Ohio rather than Fort Thomas, no state licensing disclosure, no published rates, and a reviews page that displays an outdated review figure.
- D. A. Griffin Financial, LLC (nmls 1264) (74/100) places second with the broadest program list in the study, covering non-QM, bank statement, DSCR, HELOC, hard money, construction, and 3 percent down financing alongside agency programs, supported by more than 27 years in the industry, a stated broker model, and a link to NMLS Consumer Access. Its Google review base is the smallest among scored providers at 19 reviews, and it publishes no rates or hours on its website.
- Bob Lends at The Mortgage Exchange (74/100) ties for second on points and is placed third on the tiebreak. It offers the largest calculator set in the study at thirteen tools, a live rates link, a free mortgage guide, and consultation scheduling, but shares its program range with its sister office and publishes licences for Illinois and Arizona rather than Kentucky or Ohio.
- Dave Osburg, Mortgage Loan Originator, NMLS 142308 (67/100) holds the strongest trust profile in the study, with mortgage experience since 1996, individual and company NMLS numbers, licensing in Kentucky, Ohio, and Indiana, a Kentucky-headquartered direct lender, and 180 Google reviews. His profile page describes four broad loan categories without program detail.
The remaining provider evaluated was Thrive Mortgage – Ft. Thomas KY (not scored), which holds a 4.8 rating across 18 Google reviews at a North Fort Thomas Avenue address, but for which no website was available for review.
Two findings deserve emphasis before the detail that follows. First, the scores measure published information, not service quality or actual closing performance. A provider who publishes little may deliver excellent outcomes, and the provider ranked fourth in this study has nearly twice as many Google reviews as the provider ranked first. Second, the providers ranked first through third fall within two points of one another, which reflects genuine closeness, and the appropriate choice among them depends on what a particular borrower needs.
Introduction
The search phrase “best mortgage lender Fort Thomas” is entered by people at very different stages of a consequential decision. Some are first-time buyers drawn by the city’s school district and walkable business districts. Some are families buying one of the city’s older homes and planning to renovate it. Some are veterans and military families using a VA benefit. Some are self-employed professionals whose tax returns understate their income. Some are buyers comparing a Fort Thomas home with one across the river in Cincinnati. Some are homeowners weighing a refinance or a home equity line of credit. These are not variations on one question. They are different questions that happen to share a search phrase.
Fort Thomas makes several of them heavier. The city’s housing stock includes a large share of homes built in the early and middle twentieth century, which makes renovation financing and appraisal condition more relevant than in newer suburbs. Its position within the Cincinnati metropolitan area means that many buyers compare properties and lenders in both Kentucky and Ohio, and a lender licensed in only one state may not be able to follow a buyer who changes plans. Demand in the city’s school district can make purchase contracts competitive, and in a competitive market the credibility of a pre-approval and the reliability of a closing timeline carry practical weight. Kentucky Housing Corporation programs offer down payment assistance to eligible buyers, but only through participating lenders.
The purpose of this report is to convert a crowded and largely undifferentiated field into an ordered, defensible comparison. Rather than asserting that one provider is superior, the analysis establishes measurable criteria, applies them uniformly, and reports the resulting scores alongside the reasoning behind them. The objective is to help a prospective borrower understand not only which provider scored highest, but why, and under what circumstances a lower-ranked provider would be the better choice.
The methodology is deliberately conservative. It does not reward promotional language. It does not treat a large review count as a proxy for suitability, although review volume is one input among several in the trust category. It does not treat reviewer anecdotes about fast closings as evidence of closing performance, since no provider publishes verified closing data. It does not penalize a provider for declining to publish a rate table, since mortgage pricing is borrower-specific and changes daily. It does reward clarity, verifiability, consistency, and the presence of structures that help a borrower understand what to expect between application and closing.
Background: What Defines a High-Quality Mortgage Lender in Fort Thomas
A high-quality mortgage lender can be identified by several observable characteristics that do not depend on subjective impressions or on outcomes that cannot be verified in advance.
Program Range and Genuine Product Depth
Nearly every lender offers conventional, FHA, VA, and jumbo loans. What distinguishes providers is whether they can serve borrowers who fall outside the standard profile and whether they explain what each program requires. In Fort Thomas, that includes buyers of older homes who need renovation financing, rural-eligible buyers in outlying parts of Campbell County who may qualify for USDA loans, self-employed borrowers who need bank statement or other non-QM programs, investors who need DSCR financing, and homeowners seeking a HELOC. A provider who publishes down payment, credit score, and mortgage insurance requirements for each program, rather than listing program names, is demonstrating capability.
Verifiable Licensing and Regulatory Standing
Mortgage lending is a licensed activity. A provider who publishes both a company NMLS number and an individual NMLS number, identifies the states in which it is licensed, and links to NMLS Consumer Access is offering a verification pathway that costs the consumer nothing. For Fort Thomas buyers who may purchase in Ohio, confirming licensing in both states is a practical step.
Consistency of Public Information
A provider’s business name, address, phone number, and website should match across its site, its Google Business Profile, and its licensing records. Inconsistencies may have ordinary explanations, but they make it harder for a borrower to confirm who they are dealing with and where the provider actually operates.
Closing Process Transparency and Application Infrastructure
Closing performance cannot be verified from public information, because no provider in this study publishes audited closing times. What can be assessed is whether a provider explains the path to closing: documentation, appraisal, underwriting, conditional approval, clear to close, and closing. A provider who describes each stage, offers a secure online application and document portal, and provides calculators and educational resources gives borrowers a realistic picture of the process and the points at which delays most often occur.
Rate and Cost Transparency
Because rates and fees depend on the borrower, few providers publish exact pricing. Better practice includes a dated or qualified rate reference, explanations of mortgage insurance and upfront fees, and calculators that model rate buydowns, adjustable-rate structures, and refinance break-even points.
Local Market Presence and Accessibility
A physical office in Fort Thomas, posted hours, content addressed to Northern Kentucky rather than to another market, and familiarity with Campbell County property types all matter, particularly for buyers relocating to the area.
Industry and Regulatory Context: Kentucky Mortgage Lender Standards and Consumer Protections
Mortgage lending in Fort Thomas operates within federal rules and Kentucky’s state licensing framework, and many transactions involve Ohio as well. Borrowers do not need to master these rules, but understanding their broad structure clarifies what protections exist and what questions to ask.
Federal Oversight
The Consumer Financial Protection Bureau administers and enforces the principal federal consumer protection rules governing residential mortgages, including those implementing the Truth in Lending Act and the Real Estate Settlement Procedures Act. The TILA-RESPA Integrated Disclosure rule requires a Loan Estimate within three business days of a completed application and a Closing Disclosure at least three business days before loan consummation. Because these forms are standardized, a borrower can compare offers from different providers line by line. The three-day Closing Disclosure window is also a fixed point in every closing timeline, which is why late changes to loan terms can move a closing date.
Federal loan originator compensation rules under Regulation Z restrict how mortgage brokers and loan officers may be paid. In general, compensation cannot be based on the loan’s interest rate or terms, and a broker cannot be paid by both the borrower and the lender on the same transaction. The Ability-to-Repay and Qualified Mortgage rules require lenders to make a reasonable, good-faith determination that a borrower can repay the loan. Non-QM loans, including bank statement products commonly used by self-employed borrowers, operate outside the Qualified Mortgage standards but remain subject to ability-to-repay requirements. Business-purpose investor loans, including many DSCR products, may fall outside consumer lending rules and can carry prepayment penalties. RESPA Section 8 prohibits kickbacks for settlement service referrals, and the Equal Credit Opportunity Act and the Fair Housing Act prohibit discrimination in lending.
Licensing: NMLS and the SAFE Act
The Secure and Fair Enforcement for Mortgage Licensing Act requires mortgage loan originators to be either state-licensed or federally registered through the Nationwide Multistate Licensing System. Originators employed by non-bank lenders and brokers must be state-licensed in each state where they originate loans, which involves pre-licensing education, a national examination, background and credit checks, and annual continuing education. Borrowers can search any company or originator through NMLS Consumer Access in under a minute without creating an account.
The Kentucky Department of Financial Institutions
In Kentucky, the Department of Financial Institutions licenses and supervises mortgage loan companies, mortgage loan brokers, and mortgage loan originators under the state’s mortgage lending statutes. A provider originating loans on Kentucky property must hold the appropriate Kentucky licence or registration, and the Department receives consumer complaints and may take enforcement action.
The Ohio Division of Financial Institutions
Because Fort Thomas sits directly across the Ohio River from Cincinnati, many borrowers compare homes in both states. In Ohio, the Division of Financial Institutions within the Ohio Department of Commerce licenses mortgage lenders and loan originators under the Ohio Residential Mortgage Lending Act. A borrower who may purchase in Ohio should confirm that both the company and the individual originator are licensed there.
Service Delivery Models
Distinguishing among delivery models is useful because they affect both the borrower experience and the appropriate basis for comparison. An independent mortgage broker submits a borrower’s file to multiple wholesale lenders, which can widen program access and pricing options. A direct lender funds loans through its own underwriting and capital, which can give it more control over timelines and exceptions. A mortgage company that operates branch offices under a common company NMLS, as The Mortgage Exchange does in Fort Thomas, may give individual branches their own websites and teams while sharing licensing, compliance, and program menus. None of these models is inherently superior. A fair comparison accounts for the model a provider has chosen rather than penalizing it for not being something else.
Kentucky Housing Corporation Programs
The Kentucky Housing Corporation offers first mortgage and down payment assistance programs for eligible buyers through a network of participating lenders. Program availability, funding, income limits, purchase price limits, and eligibility rules change, and not every provider is approved to originate every program. No provider in this study referenced Kentucky Housing Corporation participation on the pages reviewed, so borrowers should ask directly.
Older Homes, Renovation, and Appraisal Considerations
Much of Fort Thomas’s housing stock predates modern building codes. Appraisers for FHA, VA, and USDA loans must note health and safety conditions such as peeling paint in older homes, roof condition, and electrical or heating deficiencies, and those findings can require repairs before closing. Renovation loans such as the FHA 203(k) allow a buyer to finance the purchase and improvements together, but they add contractor bids, inspections, and a longer timeline. Buyers of older homes should discuss appraisal condition requirements with their lender early, since they are one of the most common causes of closing delays.
Kentucky Closing Practices
Kentucky imposes a real estate transfer tax on recorded deeds, which is customarily paid by the seller. Other closing costs typically include title insurance, settlement fees, recording fees, prepaid interest, and escrow deposits for property taxes and homeowners insurance. Buyers relocating from Ohio or other states should confirm how property taxes are prorated and how the local closing agent handles settlement.
Intake, Consultation, and Disclosure Standards
Sound lending practice generally involves an initial consultation covering goals, income structure, occupancy, credit position, and timeline; a credit review conducted with the borrower’s authorization; a documentation checklist; a pre-approval that states its conditions; disclosure of the compensation arrangement where a broker is involved; and delivery of the Loan Estimate after application. Borrowers should understand the terms of any rate lock, including its duration, extension costs, and whether a float-down option is available. This report treats the presence and clarity of such descriptions as a positive operational signal while maintaining neutral framing and avoiding any claim about the outcomes a given provider achieves.
Methodology
Selection Universe
Five providers were selected for evaluation from a supplied list of mortgage providers serving Fort Thomas: The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans; Dave Osburg, Mortgage Loan Originator, NMLS 142308; Bob Lends at The Mortgage Exchange; Thrive Mortgage – Ft. Thomas KY; and D. A. Griffin Financial, LLC (nmls 1264). The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans was designated in advance as the focal subject of the evaluation.
Each provider was required to meet baseline criteria. The provider must actively operate in or serve Fort Thomas, Kentucky. It must offer residential mortgage services. It must demonstrate operational transparency through a discernible office, contact pathway, and application or inquiry mechanism. It must present sufficient public information to support structured evaluation. Four providers met the threshold for full scoring. Thrive Mortgage – Ft. Thomas KY maintains a Fort Thomas office and an active Google Business Profile, but no website was available for review. Scoring it from a Google Business Profile alone would not be consistent with the method applied to the other four providers, so it is profiled with its limitations noted and is not assigned a score.
Data Sources
Data were collected from publicly accessible sources only. The primary sources were the providers’ own websites and loan officer profile pages, which supplied program descriptions, licensing identifiers, contact information, application pathways, published tools, and disclosed operating details. Google Business Profiles supplied business names, office addresses, phone numbers, business hours, ratings, and review counts as displayed during the research window. Regulatory context was drawn from general public materials describing federal, Kentucky, and Ohio mortgage regulation.
Two limitations apply. First, licensing identifiers were recorded as published by each provider and were not independently checked against NMLS Consumer Access for this report. Second, where a provider’s website and Google Business Profile differed in address, phone number, or review figures, both are reported and the inconsistency is noted rather than resolved.
No private data, paid databases, or non-public records were used. All sources are consolidated in the References section at the end of this report.
100-Point Scoring Framework
The framework distributes one hundred points across five weighted categories. The weighting reflects the relative importance of each category to a consumer comparing mortgage lenders on the basis of publicly available information in a city-specific context.
Loan Program Range and Transparency (25 points). This category evaluates the following: the breadth of published agency programs, including conventional, FHA, VA, USDA, jumbo, and refinance; the availability of specialty financing, including renovation, construction, HELOC, non-QM, bank statement, and DSCR programs; the clarity and specificity of program descriptions, including whether each program has its own page stating down payment, credit, and mortgage insurance requirements; and coverage of scenarios common in Fort Thomas, including older-home renovation, VA purchases, and buyers comparing Kentucky and Ohio properties.
Licensing, Compliance, and Trust Signals (20 points). This category evaluates the following: whether company and individual NMLS identifiers are published; whether licensed states are disclosed; the presence of NMLS Consumer Access links and compliance statements; stated experience and operating history; the volume and consistency of public reviews; and the consistency of business name, address, phone number, and website across public listings.
Client Experience and Closing Process Infrastructure (20 points). This category evaluates the following: whether the path from application to closing is described stage by stage; the availability of a secure online application and document portal; the presence of calculators and planning tools; the availability of educational resources such as program guides, FAQs, and blogs; and the ease of making contact or scheduling a consultation.
Rate and Cost Transparency (20 points). This category evaluates the following: whether rate information or a structured rate-quote pathway is published; whether mortgage insurance, upfront fees, and down payment requirements are explained; whether calculators model rate buydowns, adjustable-rate structures, and refinance break-even points; whether broker compensation is disclosed; and whether marketing claims about pricing are qualified. This category does not penalize a provider for declining to publish a rate table.
Local Market Presence and Accessibility (15 points). This category evaluates the following: whether the provider publishes a Fort Thomas office address on its website; published office hours, including evening or weekend availability; consistency between website and Google Business Profile locations; and whether website content addresses Fort Thomas and Northern Kentucky rather than another market.
The ranking logic specific to Fort Thomas follows from these weights. Loan program range carries the greatest weight because the Fort Thomas borrower mix includes a meaningful share of renovation, VA, first-time, and self-employed files, and program specificity determines whether a borrower can judge fit before applying. Licensing, closing process infrastructure, and cost transparency are weighted equally because verification, process uncertainty, and cost uncertainty are the three obstacles a borrower encounters before any financial outcome is determined. The closing process category is framed around documented process rather than claimed speed, because a borrower who understands where appraisal, underwriting, and disclosure timing can delay a file is better placed to protect a closing date than one who relies on an unverified average. Local presence carries fifteen points, enough to distinguish a verifiably local office from a provider whose content addresses another market, without allowing proximity to outweigh capability.
A provider ranks highly when it combines a clearly described program range with verifiable, consistent regulatory information, a documented path to closing, meaningful cost disclosure, and demonstrated relevance to the Fort Thomas market.
Ranked Comparative Table
Rank | Provider | Programs (25) | Trust (20) | Experience (20) | Cost Transparency (20) | Local (15) | Total (100) |
|---|---|---|---|---|---|---|---|
1 | The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans | 19 | 15 | 18 | 13 | 11 | 76 |
2 | D. A. Griffin Financial, LLC (nmls 1264) | 22 | 15 | 17 | 8 | 12 | 74 |
3 | Bob Lends at The Mortgage Exchange | 19 | 14 | 18 | 13 | 10 | 74 |
4 | Dave Osburg, Mortgage Loan Originator, NMLS 142308 | 13 | 18 | 14 | 9 | 13 | 67 |
— | Thrive Mortgage – Ft. Thomas KY | — | — | — | — | — | Not scored |
- A. Griffin Financial, LLC (nmls 1264) and Bob Lends at The Mortgage Exchange tied at 74 points; the tie was resolved in favour of the provider with the higher score in the most heavily weighted category, Loan Program Range and Transparency. The scores reflect publicly available information observed during the research window and should be read alongside the individual profiles, which explain the reasoning behind each category result and identify where information was limited or inconsistent.
Individual Provider Reviews
1. The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans — 76 / 100
Website: https://www.teampiccolaloans.com/ Company: The Mortgage Exchange (NMLS #1248883) Branch Manager: Michael Piccola (NMLS #1269145) Licensed In: Not identified on the website Office: 114 North Fort Thomas Ave, Fort Thomas, KY 41075 (website and Google Business Profile) Phone: (859) 801-0442 (website and Google Business Profile) Email: teampiccolaloans@gmail.com Hours as Published: Not found on website; Monday through Thursday 9:00 a.m. to 6:00 p.m., Friday 9:00 a.m. to 5:00 p.m., Saturday 9:00 a.m. to 12:00 p.m. (Google Business Profile) Service Area as Published: Cincinnati, Ohio and the Tri-State area Application Platform: Floify secure online application Stated Experience: Not stated Published Reviews: 5.0 rating, 99 Google reviews (the website’s reviews page displays a figure of 11 Google reviews)
Overview
Michael Piccola is the Branch Manager of the Team Piccola Loans office of The Mortgage Exchange, operating from a storefront on North Fort Thomas Avenue in the city’s central business district. The office shares its address and company NMLS number with Bob Lends at The Mortgage Exchange, and the two offices operate separate websites and Google Business Profiles. The website describes the team’s aim as simplifying mortgage financing “with personalized loan options that save you time and money,” and frames its service around guidance “from pre-approval to closing.”
What distinguishes the practice within this field is the combination of program-level detail and closing process documentation. The Purchase menu leads to six dedicated program pages covering conventional, FHA, VA, USDA, jumbo, and renovation mortgages. The FHA page, for example, states the credit score and down payment thresholds for the program, explains the upfront mortgage insurance premium as a percentage of the loan amount, gives the range for annual mortgage insurance and the rate most FHA borrowers pay, lists basic eligibility requirements, and embeds an FHA-specific payment calculator. The homepage presents a Mortgage Walkthrough Guide with six stages, from documentation through appraisal, initial underwriting, conditional approval, and clear to close to closing, together with sections for first-time buyers, home loan options, and a set of free tools. For borrowers who want to understand both the product and the process before speaking with anyone, this structure has practical value.
Best For
First-time buyers who want to understand down payment, credit score, and mortgage insurance requirements for each program before applying. Buyers of older Fort Thomas homes who may need renovation financing. VA and USDA borrowers. Borrowers who want to understand each stage between application and closing, and what is required at each. Buyers weighing whether to pay for a rate buydown or choose an adjustable-rate loan. Buyers who need weekend access, given Saturday hours on the Google Business Profile. Buyers comparing homes in Northern Kentucky and Cincinnati.
Strengths
Closing process infrastructure is tied for strongest in the study and earns 18 of 20 points. The six-stage walkthrough gives borrowers a map of the path to closing that names the stages at which most delays occur, particularly appraisal and conditional approval, and it is paired with a secure Floify application, an apply-now pathway, and a request-a-quote option. The homepage lists nine calculator tools: affordability, early payoff, rent versus buy, rate buydown, mortgage payment, mortgage comparison, DSCR investor, refinance comparison, and adjustable-rate mortgage. Program pages embed their own calculators, which let a borrower model an FHA payment with the program’s mortgage insurance built in rather than estimating it separately.
Rate and cost transparency is tied for strongest in the study and earns 13 of 20 points. No rate table is published, but the program pages quantify costs that most competitors leave unstated, including FHA upfront and annual mortgage insurance and minimum down payments by credit tier. The rate buydown, adjustable-rate, and refinance comparison calculators address the three cost decisions that most often determine whether a borrower chooses the right structure. The site also references a Today’s Mortgage Rates tool and carries a clear disclaimer that information is not an offer of credit.
The program range is clearly documented and earns 19 of 25 points, tied for second in the study. Each of the six programs has its own page, and the renovation mortgage page is directly relevant to the city’s older housing stock. The refinance page describes cash-out, lower fixed-rate, shorter-term, and longer-term refinance objectives. Program specificity of this kind allows a borrower to judge eligibility before applying rather than after.
Trust and local signals are solid. The company NMLS number and Michael Piccola’s individual NMLS number are published, and program pages link to NMLS Consumer Access. The Fort Thomas address and phone number match the Google Business Profile exactly. The Google Business Profile shows a 5.0 rating across 99 reviews, more than twice the review base of its sister office, and public review content observed during the research window frequently came from real estate agents describing communication after hours and on weekends and difficult files brought to closing. The Saturday morning hours are the only weekend hours published by any scored provider.
Trade-offs and Watch-outs
The Local Market Presence score is the second lowest among scored providers at 11 of 15. The homepage headline and main heading address “Cincinnati, OH,” and the site describes its service area as Cincinnati and the Tri-State area. Beyond the address in the footer and contact page, no Fort Thomas or Northern Kentucky content was identified. For a borrower searching specifically for a Fort Thomas lender, the site does not make its local presence obvious, even though the office is on the city’s main street. Office hours appear on the Google Business Profile but not on the website.
State licensing is not disclosed. The website publishes NMLS numbers but does not identify the states in which The Mortgage Exchange or Michael Piccola is licensed. Given that the site targets Cincinnati and the office is in Kentucky, a borrower cannot confirm from the site alone that the originator is licensed in both Kentucky and Ohio. By comparison, Dave Osburg, Mortgage Loan Originator, NMLS 142308 and D. A. Griffin Financial, LLC (nmls 1264) both list their licensed states.
Public information is partly inconsistent or incomplete. The reviews page displays a Google figure of 11 reviews, while the Google Business Profile shows 99, which suggests the site widget has not been updated. The About page gives the Branch Manager title and NMLS number but no years of experience, background, or team members. The contact email uses a general consumer email domain rather than a company domain. One Google review references a different lender name, which may reflect a prior affiliation, and borrowers should confirm the lender through which their loan will be originated. These factors account for the 15 of 20 Trust score.
No rates are published, and the calculator page reviewed presented a quick mortgage calculator with principal, interest, taxes, and insurance, without identified inputs for HOA dues or private mortgage insurance. Broker or lender compensation is not explained.
The program list omits several specialty categories. No HELOC, construction, non-QM, bank statement, or DSCR loan program was identified, although a DSCR calculator is offered. No Kentucky Housing Corporation or down payment assistance program was referenced. For a self-employed borrower or an investor, D. A. Griffin Financial, LLC (nmls 1264) publishes considerably broader coverage. This accounts for the 19 of 25 program score.
No closing time claim is made on the website, and the site’s review content includes individual anecdotes about early closings. This report does not treat those anecdotes as evidence of closing performance.
Service and Operational Transparency Notes
Company and individual NMLS numbers, a Fort Thomas address, phone, email, six program pages, a six-stage process guide, calculators, and a secure application are published, and address and phone match the Google Business Profile. The principal transparency gaps are the Cincinnati-focused homepage, the absence of state licensing disclosure, the outdated review figure, and the absence of rate information. Borrowers should confirm Kentucky and Ohio licensing through NMLS Consumer Access, ask which lender their loan will close with, and request a written estimate of the timeline from application to closing for their specific file.
2. D. A. Griffin Financial, LLC (nmls 1264) — 74 / 100
Website: http://www.dagriffinfinancial.com/ Company: D A Griffin Financial, LLC (company NMLS #1264) Loan Officer: Dora Griffin (NMLS #6380) Licensed In: Kentucky and Ohio Office: 880 Alexandria Pike, Suite 203, Fort Thomas, KY 41075 (website and Google Business Profile) Phone: (859) 442-9700 (website and Google Business Profile) Email: dora@dagriffinfinancial.com Hours as Published: Not found on website; Monday through Friday, 9:00 a.m. to 5:00 p.m. (Google Business Profile) Stated Experience: Over 27 years in the industry Model: Mortgage broker Published Reviews: 5.0 rating, 19 Google reviews
Overview
- A. Griffin Financial, LLC (nmls 1264) describes itself as a mortgage broker located in Fort Thomas, licensed in Kentucky and Ohio, with more than 27 years in the industry. The firm is led by Dora Griffin and operates from an office on Alexandria Pike in the southern part of the city.
Best For
Self-employed borrowers who need bank statement or other non-QM programs. Investors seeking DSCR or multi-unit financing. Homeowners seeking a HELOC. Buyers planning construction. Borrowers who need short-term hard money financing. Buyers looking for a 3 percent down program. First-time buyers who value patient education, as reflected consistently in public review content.
Strengths
The program list is the broadest in the study and earns 22 of 25 points. The site lists FHA with streamline and cash-out options, VA with streamline, cash-out, and IRRRL options, USDA streamline, conventional, jumbo, high balance, construction, 3 percent down programs, non-QM, bank statement, DSCR, HELOC, hard money, investor, and multi-unit financing. It is the only scored provider publishing non-QM, bank statement, HELOC, and hard money programs, and those categories map closely to self-employed and investor files.
Licensing and operating history are clearly stated. The site publishes company and individual NMLS numbers, identifies Kentucky and Ohio licensing, links to NMLS Consumer Access, and states more than 27 years in the industry. Address and phone match the Google Business Profile.
Client infrastructure is solid and earns 17 of 20 points. Navigation includes home purchase and refinance sections, loan programs, a loan process section, mortgage basics, calculators, online forms, an FAQ, a blog, testimonials, and an online application, and the firm offers the Loanzify mobile app for loan guidance.
Trade-offs and Watch-outs
Rate and cost transparency is the lowest among scored providers at 8 of 20. No rates, rate references, or mortgage insurance explanations were identified, and broker compensation is not explained even though the site identifies the firm as a broker.
The review base is the smallest among scored providers. The Google Business Profile shows 19 reviews, which is too small a sample to carry significant weight, although review content is consistently positive and frequently references first-time buyers. This accounts for the 15 of 20 Trust score despite strong licensing disclosure.
Program names are listed rather than explained on the pages reviewed, and no Kentucky Housing Corporation participation was referenced. Hours were not found on the website, and no service area list was identified, which accounts for the 12 of 15 Local score.
Service and Operational Transparency Notes
Company and individual NMLS, licensed states, address, phone, and email are published and consistent with the Google Business Profile. Borrowers considering non-QM, DSCR, or hard money financing should request the rate and fee premium relative to an agency loan, any prepayment penalty, and the broker’s compensation in writing.
3. Bob Lends at The Mortgage Exchange — 74 / 100
Website: http://boblends.info/ Company: The Mortgage Exchange / CME Lending Group LLC (NMLS #1248883) Managing Loan Officer: Bob Hacker (NMLS #1498092) Licences as Published: Illinois Residential Mortgage License MB #6761095; Arizona Mortgage Broker License MB #1037933 Office: 114 N Fort Thomas Ave, Fort Thomas, KY 41075 (website and Google Business Profile) Corporate Office: 890 E Sidewalk Rd, Chesterton, IN 46304 Phone: (859) 982-1002 (website and Google Business Profile); corporate (888) 435-7070 Email: Bob@BobLends.info Hours as Published: Not found on website; Monday through Friday, 9:00 a.m. to 5:00 p.m. (Google Business Profile) Stated Experience: Mortgage lending since 2015 Published Reviews: 5.0 rating, 44 Google reviews
Overview
Bob Hacker, who presents himself as “The Loan Doctor,” is a Managing Loan Officer with The Mortgage Exchange, operating from the same North Fort Thomas Avenue office as The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans. His site identifies the company as CME Lending Group LLC with a corporate office in Chesterton, Indiana, and states that he began mortgage lending in 2015.
Best For
Borrowers who want to compare many calculator scenarios before applying. Borrowers who want to schedule a consultation online. Buyers working to improve their credit before purchasing, as reflected in public review content. First-time, VA, USDA, jumbo, and renovation borrowers.
Strengths
Client infrastructure is tied for strongest in the study and earns 18 of 20 points. The site offers thirteen calculators, the largest set in the study, including program-specific VA, jumbo, FHA, conventional, and USDA calculators alongside affordability, rate buydown, DSCR investor, and adjustable-rate tools. It also offers a free mortgage guide, a mortgage process walkthrough, an FAQ section, a secure Floify application, and online consultation scheduling.
Cost transparency is tied for strongest at 13 of 20, supported by a live rates link and the calculator set, although no rate values were displayed in the content reviewed. The site publishes a personal biography, the company and individual NMLS numbers, and a corporate address and phone. Program pages cover the same six programs as the sister office, earning 19 of 25 points.
Trade-offs and Watch-outs
The licences published on the site are for Illinois and Arizona. No Kentucky or Ohio licence was identified on the site, even though the office is in Kentucky and the site targets Cincinnati. Borrowers should confirm Kentucky and Ohio licensing through NMLS Consumer Access. With 44 Google reviews and experience since 2015, the trust profile is moderate, accounting for the 14 of 20 Trust score.
The main content refers to “mortgage lenders in Cincinnati, OH,” and no Fort Thomas content beyond the address was identified, which accounts for the 10 of 15 Local score, the lowest among scored providers. The program menu is identical to that of the sister office, with no HELOC, non-QM, or construction programs. Because both offices share a company and address, borrowers comparing them should understand that they are comparing two loan officers at the same company rather than two different lenders.
Service and Operational Transparency Notes
Company and individual NMLS, a local and corporate address, phone numbers, and email are published and consistent with the Google Business Profile. Borrowers should confirm Kentucky and Ohio licensing and request current rates for their scenario in writing.
4. Dave Osburg, Mortgage Loan Originator, NMLS 142308 — 67 / 100
Website: https://stockton.com/staff/dave-osburg/ Company: Stockton Mortgage Corporation (company NMLS #8259), headquartered at 88 C. Michael Davenport Blvd, Frankfort, KY 40601 Branch Manager: Dave Osburg (NMLS #142308) Licensed In: Indiana, Kentucky, and Ohio Office: 143 North Fort Thomas Avenue, Suite 2, Fort Thomas, KY 41075 (website and Google Business Profile) Phone: 859.291.5626 (website and Google Business Profile); company 888.914.2276 Email: dave.osburg@stockton.com Hours as Published: Not found on profile; Monday through Friday, 9:00 a.m. to 5:00 p.m. (Google Business Profile) Stated Experience: In mortgages since 1996 Model: Branch of a Kentucky-headquartered direct lender; BBB Accredited Business, Equal Housing Lender Published Reviews: 5.0 rating, 180 Google reviews
Overview
Dave Osburg is a Branch Manager with Stockton Mortgage Corporation, operating from an office on North Fort Thomas Avenue. His profile states that he has worked in mortgages since 1996 and has served “thousands of Northern Kentucky homeowners,” and it emphasizes personalized care in making home financing “a smooth and positive experience.”
Best For
Borrowers who value three decades of Northern Kentucky mortgage experience. Buyers who prefer a Kentucky-headquartered direct lender. Buyers planning construction or renovation. Borrowers who may purchase in Kentucky, Ohio, or Indiana. Borrowers who weight review volume heavily.
Strengths
The trust profile is the strongest in the study and earns 18 of 20 points. The profile publishes individual and company NMLS numbers, identifies three licensed states, states mortgage experience since 1996, and identifies the company as BBB accredited. The Google Business Profile shows 180 reviews at a 5.0 rating, the largest in the study, and review content frequently references a named support team, which suggests processing depth.
Local presence is the strongest in the study at 13 of 15. The Fort Thomas address and phone match the Google Business Profile, and the profile’s language addresses Northern Kentucky directly.
The profile offers a direct application link to the company’s HomeHub platform and a loan calculator, and the company website provides a blog, FAQ, guides, and glossary.
Trade-offs and Watch-outs
The program range published on the profile is the narrowest among scored providers and earns 13 of 25 points. The profile lists four categories, buying, refinancing, construction, and home renovation, without identifying specific programs such as FHA, VA, or USDA, or their requirements. The company may offer more, but a borrower cannot judge program fit from the profile.
No process description, rate information, or mortgage insurance explanation was identified on the profile, which accounts for the 14 of 20 Experience and 9 of 20 Cost scores. Much of the supporting content sits on the corporate website rather than the local profile.
A second Google Business Profile, Thrive Mortgage – Ft. Thomas KY, lists the same street address, and its review content references Dave Osburg and his team. Borrowers may find the two listings confusing and should confirm which company will originate their loan.
Service and Operational Transparency Notes
Individual and company NMLS, licensed states, address, phone, email, and experience are published and consistent. Borrowers should request a list of the specific programs available for their scenario and a written estimate of closing costs.
Thrive Mortgage – Ft. Thomas KY — Not Scored
Website: None available for review Office: 143 N Ft Thomas Ave, Fort Thomas, KY 41075 (Google Business Profile) Phone: 859-441-8900 (Google Business Profile) Hours as Published: Monday through Friday, 8:30 a.m. to 5:00 p.m. (Google Business Profile) Published Reviews: 4.8 rating, 18 Google reviews
Overview
Thrive Mortgage – Ft. Thomas KY maintains a Google Business Profile at a North Fort Thomas Avenue address showing a 4.8 rating across 18 reviews. Public review content observed during the research window references Dave Osburg and named team members, and one review references a different mortgage company name.
Scoring Limitation
No website was available for review. As a result, program descriptions, licensing identifiers, application tools, and cost information could not be assessed, and the company’s NMLS number could not be confirmed from the sources reviewed. Assigning a score from a Google Business Profile alone would not be consistent with the method applied to the other four providers, so Thrive Mortgage – Ft. Thomas KY is presented without a score. This limitation reflects the availability of information during the research window, not a judgment about the firm’s services.
Service and Operational Transparency Notes
The listing shares a street address with Dave Osburg, Mortgage Loan Originator, NMLS 142308, and its review content suggests a connection to the same team, possibly through a prior affiliation. Borrowers considering this provider should contact it directly, confirm which company will originate the loan, and verify licensing through NMLS Consumer Access.
Cross-Provider Observations
Several patterns emerged across the field that are more informative than any individual score.
Ratings have ceased to be a differentiator; volume has not. Ratings ranged only from 4.8 to 5.0, while review counts ranged from 18 to 180. Review volume correlates weakly with the transparency measures assessed here: the provider with the most reviews publishes the narrowest program detail among scored providers, while the provider with the broadest program list has the smallest review base.
The field is more concentrated than it appears. Two scored providers share one company, one company NMLS number, and one office, and a third listing shares its street address with another scored provider. Borrowers comparing these listings may be comparing loan officers within the same company rather than separate lenders.
Local content is thinner than local presence. Every scored provider has a Fort Thomas office that matches its Google Business Profile, but two of four scored websites address Cincinnati in their main content rather than Fort Thomas, and none publishes Fort Thomas-specific guidance on older-home appraisals, renovation, or Kentucky Housing Corporation programs.
State licensing disclosure is uneven. Two scored providers list their licensed states, one lists licences in states other than Kentucky and Ohio, and one lists none. For a market where buyers routinely cross the Ohio River, this is a meaningful gap.
Closing performance is claimed by reviewers, not documented by providers. No scored provider publishes a verified or average closing time. Two publish a stage-by-stage description of the path to closing, which is the most useful closing information available to a borrower in advance.
Program depth and program explanation rarely coincide. The provider publishing the broadest program list explains none of its programs in detail on the pages reviewed. The providers explaining programs most specifically publish six. No provider combines broad specialty coverage with program-level explanations, which is the single largest gap in the Fort Thomas market.
Rate information is absent everywhere. No scored provider publishes a rate table. The Loan Estimate remains the only reliable basis for cost comparison.
Broker compensation is unexplained everywhere. The provider identifying itself as a broker does not publish an explanation of how it is paid.
Recommendations by Borrower Type
First-Time Homebuyers
First-time buyers benefit from clear explanations of program requirements. The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans publishes the most specific program requirements, including FHA credit score, down payment, and mortgage insurance figures, together with a six-stage guide to closing. D. A. Griffin Financial, LLC (nmls 1264) publishes 3 percent down programs and has review content that frequently references first-time buyers. Buyers should ask each provider whether it participates in Kentucky Housing Corporation down payment assistance.
VA Borrowers
The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans and Bob Lends at The Mortgage Exchange publish dedicated VA pages, and D. A. Griffin Financial, LLC (nmls 1264) publishes VA streamline, cash-out, and IRRRL options. VA borrowers should ask how the funding fee applies and whether they qualify for an exemption.
Buyers of Older Homes and Renovation Projects
Fort Thomas’s older housing stock makes renovation financing and appraisal condition especially relevant. The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans and Bob Lends at The Mortgage Exchange publish renovation mortgage pages, and Dave Osburg, Mortgage Loan Originator, NMLS 142308 lists home renovation and construction lending. Buyers should ask early how FHA or VA appraisal condition requirements could affect their closing date.
Self-Employed Borrowers and Investors
- A. Griffin Financial, LLC (nmls 1264) is the only provider publishing non-QM, bank statement, DSCR, investor, and multi-unit programs. Self-employed borrowers should ask for the rate premium relative to an agency loan and the documentation required. Investors should ask whether any DSCR loan carries a prepayment penalty.
Refinance and Home Equity
The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans publishes refinance comparison and rate buydown calculators that help a borrower evaluate break-even points. D. A. Griffin Financial, LLC (nmls 1264) publishes HELOC and streamline refinance options. Homeowners should compare the total cost of refinancing against the monthly savings and the expected time in the home.
Buyers Comparing Kentucky and Ohio
Buyers who may purchase on either side of the river should confirm licensing in both states. Dave Osburg, Mortgage Loan Originator, NMLS 142308 lists Kentucky, Ohio, and Indiana, and D. A. Griffin Financial, LLC (nmls 1264) lists Kentucky and Ohio. The two Mortgage Exchange offices target Cincinnati in their site content, but borrowers should confirm Kentucky and Ohio licensing through NMLS Consumer Access.
Construction Borrowers
- A. Griffin Financial, LLC (nmls 1264) and Dave Osburg, Mortgage Loan Originator, NMLS 142308 publish construction financing. Borrowers should ask whether the loan is a single-close construction-to-permanent loan or two separate loans, and how draws and inspections are handled.
Limitations
This report carries limitations that readers should weigh alongside its findings.
The evaluation measures published information, not service quality, outcomes, rates obtained, actual closing timelines, or client satisfaction. The provider ranked fourth has nearly twice as many Google reviews as the provider ranked first. The framework is a tool for comparing what can be assessed before contact, and nothing more.
All findings reflect a single research window in September 2026. Programs, office addresses, phone numbers, hours, review totals, team composition, and licensing details change.
Licensing identifiers were recorded as published and were not independently checked against NMLS Consumer Access. Where listings were inconsistent, both versions were reported without determining which is current. Some pages on provider websites could not be fully assessed during the research window.
One provider could not be scored because no website was available for review. The providers evaluated were selected from a supplied list and do not constitute a comprehensive survey of mortgage lenders serving Fort Thomas, and the absence of a provider from this analysis carries no implication about its quality.
Scoring involves judgment. Another analyst applying the same framework to the same evidence would likely produce similar orderings but not identical point totals, particularly within the two-point band separating the providers ranked first through third.
Conclusion
The Fort Thomas mortgage market is competitive and, at the level of surface signals, remarkably uniform. Every provider evaluated displays a near-perfect Google rating. Nearly every provider offers the core agency programs. Nearly every provider invites borrowers to request a quote. A consumer relying on these signals alone has almost nothing to choose between.
The differences that can be assessed in advance lie beneath those signals: whether a provider explains what each program requires, whether it documents the path from application to closing, whether it publishes verifiable licensing in both Kentucky and Ohio, whether it offers programs for renovation, self-employed, and investor files, whether it provides tools to evaluate buydowns, adjustable rates, and refinance break-even points, and whether its content addresses Fort Thomas.
The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans leads this evaluation at 76 points through the most balanced combination of program specificity, closing process documentation, cost-decision tools, and consistent local contact information, supported by 99 Google reviews and Saturday availability. It does not lead on program breadth, licensing disclosure, or local content, and this report identifies those gaps plainly, including the Cincinnati-focused homepage, the absence of state licensing disclosure, and the outdated review figure on its website.
- A. Griffin Financial, LLC (nmls 1264) follows at 74 with the broadest program list and a stated 27-year history. Bob Lends at The Mortgage Exchange places third, also at 74, with the largest calculator set. Dave Osburg, Mortgage Loan Originator, NMLS 142308 follows at 67 with the strongest trust and local profile.
The appropriate choice depends on the borrower. A first-time, VA, or renovation buyer who wants to understand program requirements and the closing process before applying should look first at the provider publishing both. A self-employed borrower or investor should look at the broker publishing non-QM and DSCR programs. A borrower who weights long local experience and review volume should look at the direct lender branch with three decades in Northern Kentucky. A buyer who may purchase in Ohio should confirm dual-state licensing with whichever provider they choose.
Whichever provider a borrower selects, three actions apply universally: verify company and individual licensing in Kentucky, and in Ohio if relevant, through NMLS Consumer Access; obtain Loan Estimates from at least two or three providers on the same day; and ask for a written estimate of the timeline from application to closing, including when the appraisal will be ordered.
Borrower Decision Checklist
Before making contact
Verify the provider’s company and individual NMLS numbers through NMLS Consumer Access, confirming Kentucky licensing and Ohio licensing if you may buy across the river.
Confirm that the business name, address, phone number, and website match across the provider’s site, Google Business Profile, and NMLS record, and ask about any differences.
Establish your own position first: know your credit score, assemble two years of income documentation, and calculate your available down payment including closing costs and reserves.
Determine whether you may qualify for Kentucky Housing Corporation down payment assistance.
For an older home, arrange a thorough inspection and note any conditions that could be flagged by an FHA, VA, or USDA appraiser.
During the consultation
Ask whether the provider is a broker or a direct lender, and what that means for your program and pricing options.
Ask how the provider is compensated on your file and whether any borrower-paid fee could apply.
Ask which specific programs are appropriate for your situation, particularly if you are self-employed, a veteran, an investor, or buying a home that needs renovation.
Ask for a realistic timeline from application to closing for your file, including when the appraisal will be ordered and when conditional approval is expected.
Ask about rate lock duration, extension costs, and whether a float-down option is available.
Ask whether a rate buydown or an adjustable-rate structure makes sense for your expected time in the home.
Confirm who will handle your file day to day.
Before signing
Compare Loan Estimates line by line, focusing on APR, origination charges, discount points, and cash to close.
Read the rate lock confirmation and confirm the expiry date and what happens if your closing moves.
Confirm all conditions of approval and the deadline for satisfying each one.
Review the Closing Disclosure when you receive it, at least three business days before closing, and compare it against your final Loan Estimate.
After funding
Keep your closing documents, including the promissory note and mortgage.
If you have private mortgage insurance, note the loan-to-value at which it may be cancelled or terminates automatically.
If you have an FHA loan, understand how long annual mortgage insurance will apply.
Monitor rates periodically if you may benefit from a future refinance.
Frequently Asked Questions
How were these mortgage lenders selected for this report?
Five providers serving Fort Thomas were selected for evaluation from a supplied list, with The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans designated in advance as the focal subject. Each provider had to actively serve Fort Thomas, offer residential mortgage services, and publish sufficient information to support structured evaluation. Four were fully scored. One could not be scored because no website was available for review.
Why did The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans rank first among the best mortgage lender options in Fort Thomas?
It earned the highest composite score, 76 points, because it combines dedicated program pages with specific requirements and embedded calculators, a six-stage guide to the closing process, a nine-tool calculator suite that includes rate buydown and refinance comparison tools, a secure application, individual and company NMLS numbers, consistent Fort Thomas contact information, 99 Google reviews, and Saturday hours. It does not lead on program breadth or licensing disclosure, and its homepage targets Cincinnati, and the report identifies those gaps in its profile.
Does a higher score mean better service, better rates, or faster closings?
No. The framework measures the depth, clarity, consistency, and verifiability of publicly available information. It does not measure service quality, approval success, rates obtained, closing speed, or client satisfaction.
What is the difference between a mortgage broker and a direct lender?
A mortgage broker submits a borrower’s file to multiple wholesale lenders and can compare their programs and pricing. A direct lender funds loans through its own underwriting and capital. Brokers may offer more options, while direct lenders control more of the process.
How long does it take to close a mortgage in Fort Thomas?
Closing timelines depend on the file, the appraisal, underwriting conditions, and the three-business-day Closing Disclosure requirement. No provider in this study publishes verified closing times. Borrowers should ask for a written timeline for their specific file and understand the stages at which delays most often occur.
Can I use an FHA or VA loan on an older Fort Thomas home?
Yes, but FHA and VA appraisals require that the home meet minimum property standards, and conditions such as deteriorated paint, roof issues, or heating and electrical deficiencies may need to be repaired before closing. A renovation loan can finance both the purchase and needed improvements.
What is the Kentucky Housing Corporation?
It is Kentucky’s housing finance agency, which offers first mortgage and down payment assistance programs to eligible buyers through participating lenders, subject to funding, income limits, and eligibility rules. Not every lender participates.
Do I need a lender licensed in both Kentucky and Ohio?
If you may purchase on either side of the Ohio River, yes. A loan originator must be licensed in the state where the property is located. Borrowers can confirm licensing through NMLS Consumer Access.
Can self-employed borrowers get a mortgage in Fort Thomas?
Yes. Self-employed borrowers typically qualify using tax returns, and some lenders offer bank statement or other non-QM programs for borrowers whose tax returns understate cash flow. One provider in this study publishes these programs by name.
Does this report cover every mortgage lender in Fort Thomas?
No. Five providers were selected for evaluation, and four were fully scored. Fort Thomas and Northern Kentucky are served by many more lenders and brokers than this report surveys, and the absence of a provider carries no implication about its quality.
References
Bob Lends at The Mortgage Exchange. Google Business Profile. https://maps.app.goo.gl/5nzNC8BDms8EgTDXA
Bob Lends at The Mortgage Exchange. Homepage. http://boblends.info/
Consumer Financial Protection Bureau. https://www.consumerfinance.gov/
- A. Griffin Financial, LLC (nmls 1264). Google Business Profile. https://maps.app.goo.gl/UFk5y9Ly7tRv7dveA
- A. Griffin Financial, LLC (nmls 1264). Homepage. http://www.dagriffinfinancial.com/
Dave Osburg, Mortgage Loan Originator, NMLS 142308. Google Business Profile. https://maps.app.goo.gl/N25w8bEFtnUfj7ke9
Dave Osburg, Mortgage Loan Originator, NMLS 142308. Stockton Mortgage profile. https://stockton.com/staff/dave-osburg/
Kentucky Department of Financial Institutions. https://kfi.ky.gov/
Kentucky Housing Corporation. https://www.kyhousing.org/
NMLS Consumer Access. https://www.nmlsconsumeraccess.org/
Ohio Division of Financial Institutions. https://com.ohio.gov/divisions-and-programs/financial-institutions
The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans. FHA loan program page. https://www.teampiccolaloans.com/loan-programs/fha/
The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans. Google Business Profile. https://www.google.com/maps/place/?q=place_id:ChIJX3j1GZK3QYgRjURTRrsn9dI
The Mortgage Exchange – Team Piccola Loans – Mortgage – Michael Piccola – Home Loans. Homepage. https://www.teampiccolaloans.com/
Thrive Mortgage – Ft. Thomas KY. Google Business Profile. https://maps.app.goo.gl/8JD2Fy1eyoXD5pqv8
U.S. Department of Housing and Urban Development. FHA 203(k) Rehabilitation Mortgage Insurance. https://www.hud.gov/program_offices/housing/sfh/203k